Cash offers and investor letters: what they mean for your probate sale.
When a family loses a loved one, the mailbox often fills with "we buy houses" letters, and a cash offer can arrive before the executor has even been appointed. That is not a sign of trouble; it is simply the housing market noticing a public record. This guide walks you through what those offers really are, when cash genuinely helps a probate sale, how the probate court fits in, and how to compare offers in a way that protects your family's inheritance.
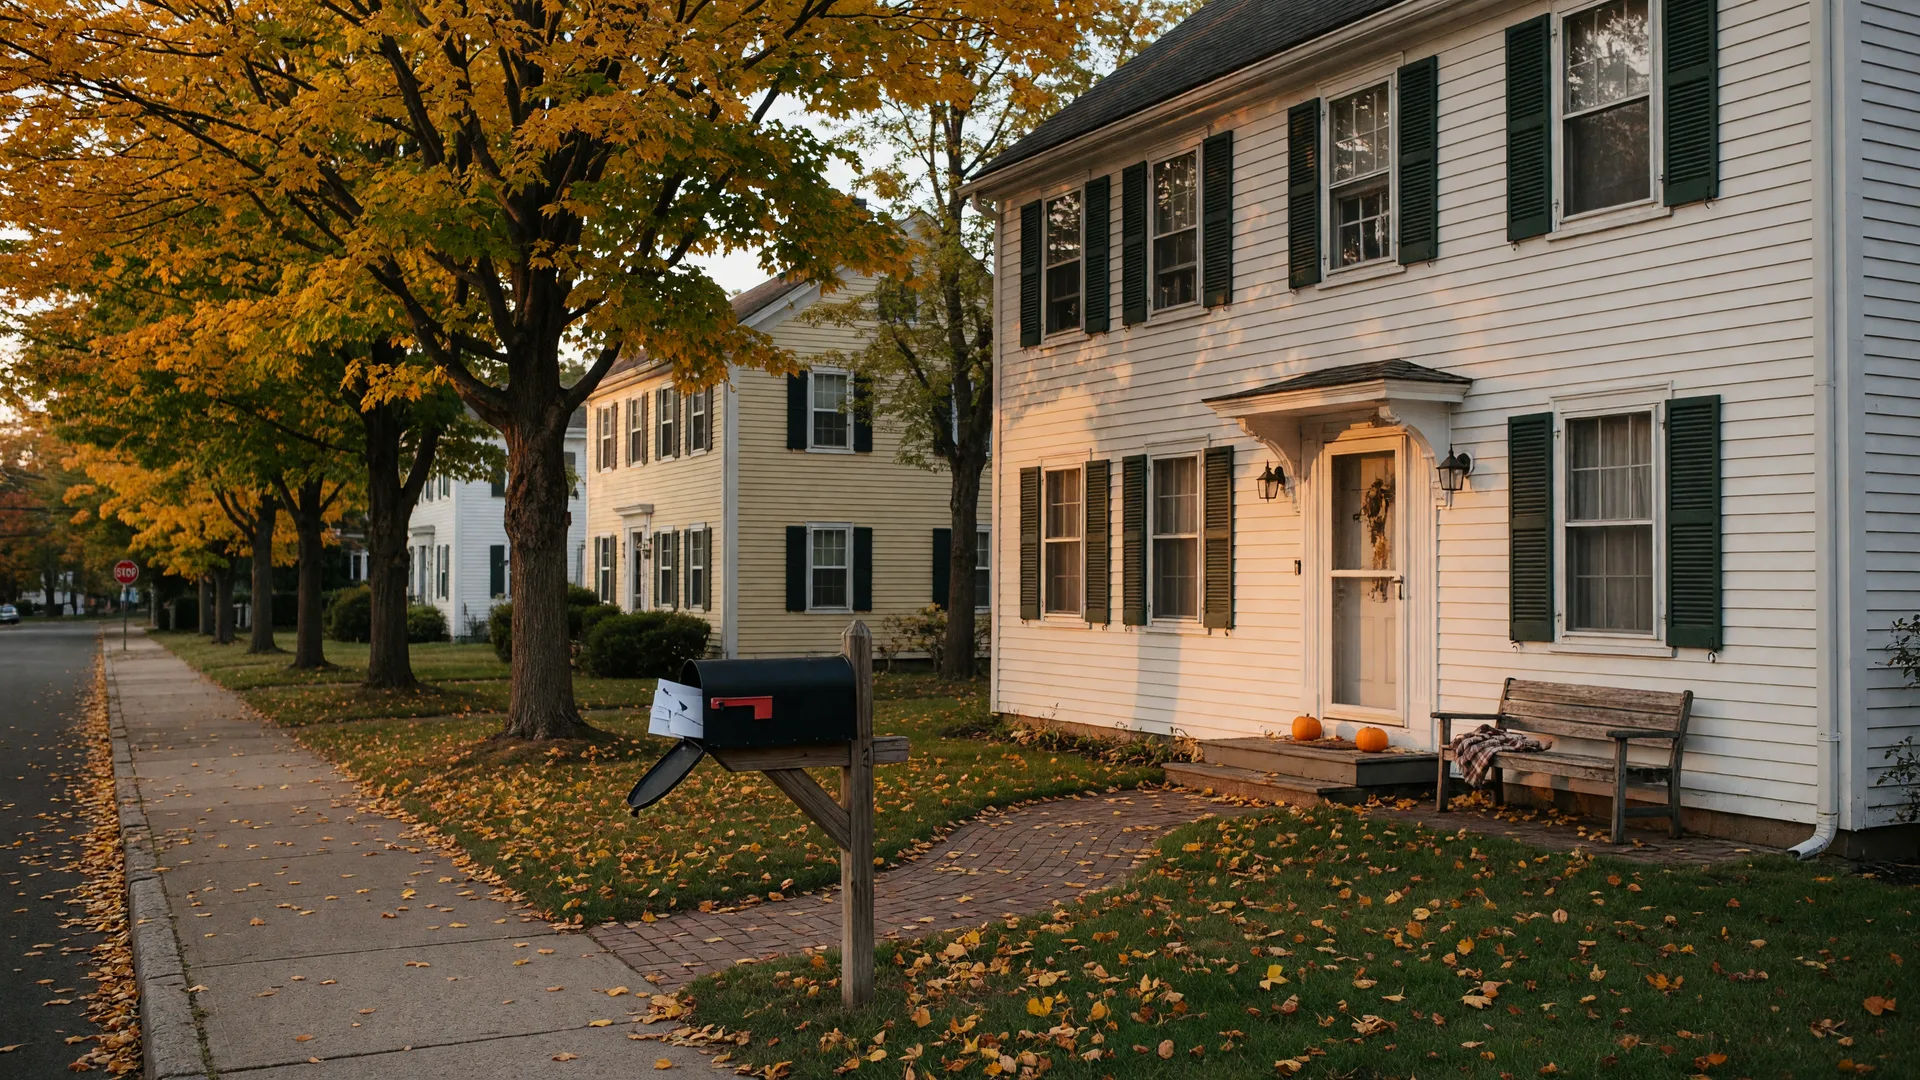
Where all these letters come from, and why your address is on the list.
If you have recently become the executor or personal representative of a loved one's estate, you have probably already seen them: bright postcards promising cash, a quick closing, and no repairs, sometimes with a handwritten-style note addressed to the estate. It can feel invasive, especially while you are still grieving. Please know this: these mailings are automatic, sent to thousands of people by computer, and they are not a commentary on your home or your family.
Probate filings and property records are public, and marketing firms buy those lists for pennies. In this year's market, cash buyers play a large enough role that the letters multiplied. Here is the backdrop:
31.4%
US sales paid in cash
All-cash purchases were 31.4% of US home sales in the first four months of 2026, down from 32.3% a year earlier, with cash deals falling faster than the overall market (Realtor.com data reported by CNBC).
~19%
Homes bought by investors
Investors bought about 19% of homes sold in 39 large metros in the first quarter of 2026, the lowest share since 2020 (Redfin), down from about 20% a year earlier.
8.8-13.9%
Below resale value at iBuyers
In early 2026, the largest instant-buyer companies averaged offers 8.8% (Opendoor) and 13.9% (Offerpad) below estimated resale value (Clever analysis), a reminder that convenience carries a price.
None of this makes an offer good or bad on its own. It simply explains why the letters show up, and why a calm, structured review matters more than a quick signature. Most importantly: only the executor or personal representative has the authority to entertain an offer for a probate property, and no one should ever pressure you to move before you understand the full picture.
What a cash offer actually is, and what it is not.
Not every cash offer comes from the same kind of buyer, and the differences matter. In broad terms:
- A mortgage-free homebuyer. A family or individual who has saved the full purchase price, or who is selling their own home first. These buyers fund with cash simply because they can, and they intend to live in the home.
- An investor. A company or individual who buys to renovate and resell, or to rent. Investors price carefully because they need a margin, so their offers tend to run below what a home would bring on the open market.
- An instant buyer, or iBuyer. A national company that makes an algorithmic offer in days. It is a small slice of the market, roughly 1% of purchases in recent years, and its offers are engineered for the company's profit, which is why they average well below resale value.
- A wholesaler. Someone who does not plan to buy the home at all. They aim to lock in your signature and then assign the contract to another buyer for a fee. Wholesale offers are frequently the lowest and add a layer of risk that a probate estate does not need.
Here is the reassuring part: in Connecticut's current market, with rates hovering near 7% and inventory very thin, plenty of traditional buyers are making strong offers, cash and financed alike. An offer that arrives in the mail is only one voice in the room. The home's real value is set by the market, not by a postcard, and there is a straightforward way to find out what the market would pay.
Watch: Steps to Selling a Probate Property
A cash offer is only one step in a larger process. This short video walks through the full sequence for a probate property in Connecticut, from executor appointment through listing, offers, and court confirmation, so you can see where an offer, in any form, fits into the journey.
When cash truly helps, and when it quietly costs you.
Cash is not a magic word, but it is a real advantage in specific situations. For a probate estate, the genuine strengths of a cash offer are speed and certainty. There is no lender, no appraisal contingency, no financing falling through in week six, and no delay while a bank reviews the estate's paperwork. Those strengths matter most when:
- The home is vacant and aging. Every month an empty house sits, it costs the estate in property taxes, insurance, heat, and general wear. A clean, fast close can be worth real money, especially heading into winter.
- The home needs significant work. A buyer who plans to renovate will pay less, but they will not ask the estate to make repairs either. If the family cannot or should not invest in updates, an as-is cash path can be the wisest route. Our guide to selling a probate home as-is walks through the trade-offs.
- Heirs live out of state. When the family is spread across the country, coordinating showings, maintenance, and repairs is exhausting. A single, clean transaction can relieve that burden in a meaningful way.
- The court timeline is tight. Connecticut's probate courts do not require a cash sale, but they do want confidence that an approved sale will actually close. An offer with financing fully committed and a substantial deposit can offer that same confidence.
Under Connecticut law, an executor must petition the probate court for permission to sell real property, using Form PC-400, and the court decides based on what is fair and prudent for the estate, not on whether the money is cash. A financed buyer with a strong commitment letter and a healthy deposit can be every bit as good a choice. When you hear "cash only," most of the time it is about the buyer's own convenience, not a rule of law, so the executor should feel free to weigh both kinds of offers honestly.
How the probate court fits in, and why confirmation protects everyone.
One of the most comforting things about probate real estate in Connecticut is that no one sells the family home alone. The process has built-in safeguards:
- 1The executor holds the pen. Only the appointed executor or personal representative can sign for the estate. No family member, no matter how well-meaning, can bind the estate, and neither can a mailed letter.
- 2The court approves the sale. The executor petitions the court with the inventory, the appraisal, and the accepted offer, and the court decides whether the terms are fair to the estate and its heirs.
- 3Other buyers can step in. At the confirmation hearing, qualified buyers may appear and overbid, which means the home can find its true value even after an offer has been accepted. Our guide to the court confirmation hearing explains exactly how this works.
This is why a cash offer is attractive to the court in the same way it is attractive to the family: fewer moving parts between approval and closing. But courts routinely approve financed sales with solid commitments, and the confirmation process protects heirs regardless of how the buyer funds the purchase. Your job is not to guess what the court wants; it is to bring the court a good, well-understood offer, and the estate attorney and your agent will guide the paperwork.
How to compare offers fairly, a simple framework for the executor.
The biggest number on the page is not automatically the best offer. Here is the framework I use with families so that every offer is judged by the same yardstick:
- Start with true value, not the letter. Have the home priced by a licensed agent using fresh comparable sales, and let the probate appraisal do its own job for the court. Our guide to probate appraisals in Connecticut explains the difference between the two numbers.
- Compare net proceeds. Subtract every expected cost, including closing costs and any repairs the buyer requests, and compare what actually reaches the estate.
- Weigh certainty. How large is the deposit? Is proof of funds provided? For financed buyers, is the commitment letter current and the lender well-established? A slightly lower offer that closes on time can beat a higher one that keeps slipping.
- Look at contingencies. Inspection, appraisal, financing, and even the sale of the buyer's own home all add time and risk. Fewer contingencies usually means a smoother path to confirmation and closing.
- Expect the market to speak. In this year's market, with New Haven homes averaging around 49 days on market and inventory very thin, a well-priced home typically draws competitive interest. If an investor letter arrives before the home is even listed, that is a signal to gather more data, not to sign in a hurry. Our fall 2026 market guide covers the current conditions in detail.
And a gentle reminder for whoever is reading this on behalf of the family: you are allowed to take your time. Offers do not expire the moment they land. A legitimate buyer, cash or financed, will still be there after the executor has consulted the estate attorney, reviewed the numbers, and felt good about the decision.
A few red flags to watch for, and how to stay protected.
Almost all of these letters are simply aggressive marketing, and most will go away if you do nothing. But a small number of solicitations cross a line, and it helps to recognize the pattern. Be cautious if a buyer or agent:
- Pushes for a decision before the appraisal. The appraisal literally exists so the estate knows what the home is worth. An offer that cannot survive a week's wait is worth questioning.
- Discourages an agent or attorney. The estate's lawyer is required for the court sale anyway, and an experienced agent keeps the process fair. Anyone who wants you to proceed without professional eyes is not looking out for the estate.
- Wants to bypass the probate process. There is no version of a Connecticut probate real estate sale that skips the court. An offer that asks you to sign outside the estate framework should not be signed at all.
- Talks in terms of what you can "walk away with today." Pressure language about deadlines, cash in hand, or "no other buyers exist" is a sales tactic. In a market this thin, the record shows the opposite: buyers are out there.
Here is the simplest protection of all: the estate's money stays under the court's watch, the executor's signature, and the family's discussion. When an offer is written, reviewed with the attorney, compared against the market, and presented to the court, the pressure dissolves, because the process itself does the protecting.
Why probate experience matters when the offers start arriving.
A cash offer is easy to understand and hard to ignore, especially when you are tired, grieving, and responsible for a home you did not ask to manage. That is exactly why an agent who knows the probate path matters. Small differences in process, paperwork, and timing add up to thousands of dollars for the estate, and the right guidance turns a stressful decision into a clear one.
An agent who works with probate families regularly can help you:
- Price the home from fresh market data so an offer can be judged against reality, not against a postcard.
- Prepare every document the court needs, from the inventory through the confirmation hearing.
- Compare cash and financed offers on equal footing, with the estate's net proceeds in view.
- Coordinate with the estate attorney so nothing about the sale surprises the family.
- Keep out-of-state heirs informed and involved at every step, with patience and clear language.
Robert Clarke
Coldwell Banker Realty · 24 Washington Ave, North Haven, CT 06473
(203) 936-9004 ·
rob@robandvicCT.com
I serve families in New Haven, Hamden, North Haven, Branford, Milford, and surrounding Connecticut communities. If a mailbox full of letters has landed on your loved one's home this season, I would be honored to help you sort through the offers with patience, candor, and care.
Your practical takeaways for the offers ahead.
Whether the first letter just arrived or the executor is already weighing offers, here is what I hope you remember:
- ✓The letters are not personal. They are automated marketing built from public records, and they say nothing about the worth of your family's home.
- ✓Only the executor can act. No letter, phone call, or family member can bind the estate without the appointed executor, and the court stays in the picture start to finish.
- ✓Cash is a tool, not a verdict. It brings speed and certainty that can be genuinely valuable for a vacant or aging estate home, and it is never required by Connecticut law.
- ✓Know the home's real value first. A comparable market analysis and the probate appraisal put every offer in perspective, and the confirmation hearing protects heirs from accepting too little.
- ✓Compare offers on paper. Net proceeds, contingencies, deposit, and timeline matter more than the headline number, and a written offer reviewed with an attorney is the only offer worth discussing.
- ✓You are not alone in this. Executors across Connecticut sort through these very letters every year, and the probate process was built to protect them. With the right team, you can decide with confidence, not pressure.
If you are caring for a loved one's home and want an honest read on what it is worth before you respond to anything, I invite you to reach out. There is no obligation and no sales pitch, just a conversation about your family's situation and how we can make the process feel lighter.
Want to talk about your specific situation?
Whether the offers are already stacking up or you are just beginning the probate process, I am here to help with honest, compassionate guidance.